Ankit
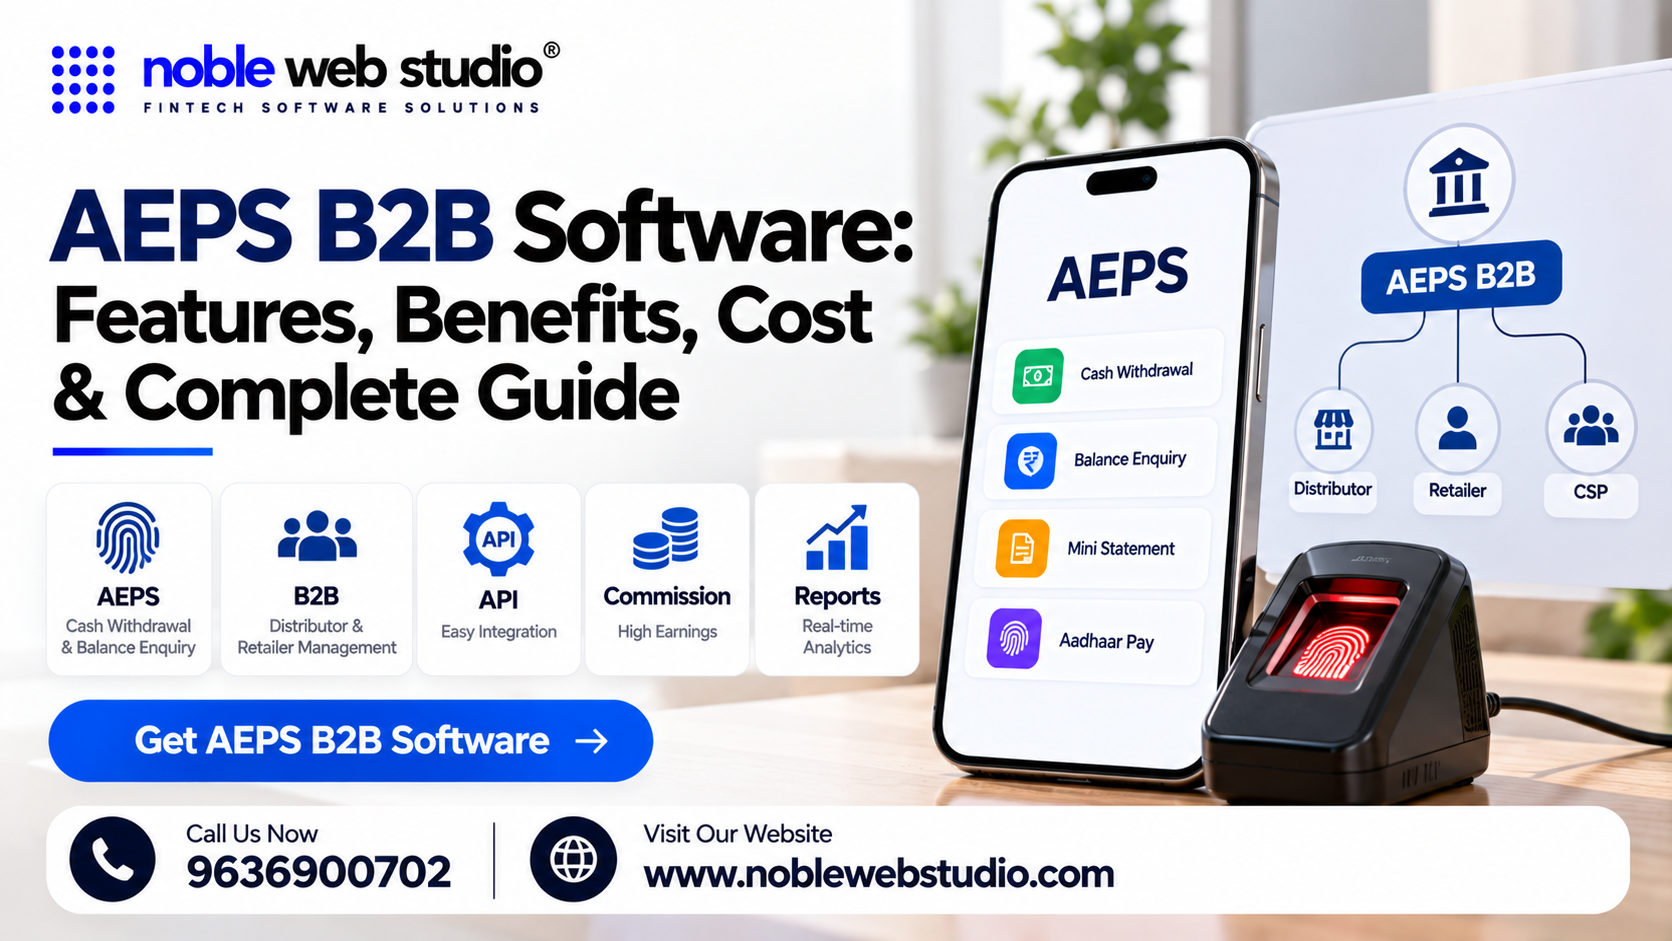
Looking for a reliable AEPS B2B Software to start or expand your digital banking business? An AEPS B2B platform helps fintech companies, service providers, distributors, and retailer networks offer Aadhaar-enabled banking services through a centralized system. Instead of managing transactions and business operations through separate tools, businesses can use one platform to manage retailers, distributors, wallets, commissions, transactions, reports, and AEPS services.
A modern AEPS B2B Software is designed for businesses that operate through a multi-level distribution network. It can provide a structured system for Master Distributor, Distributor, Retailer, and Admin management, allowing businesses to create users, assign services, configure commissions, manage wallets, monitor transactions, and control access from a centralized dashboard.
B2B AEPS software is a white-label or customized digital Aeps platform that lets businesses launch their own micro-banking and financial service networks without building bank integrations from scratch.
The core AEPS services can include cash withdrawal, balance enquiry, mini statement, fund transfer, Aadhaar Pay, cash deposit, and other supported assisted-banking services, depending on the available banking integrations and service configuration. With biometric authentication and Aeps API connectivity, an AEPS B2B platform can help retailers deliver banking services to customers through an assisted service model.
For a growing fintech business, the Aeps software needs to do more than process transactions. A complete AEPS B2B Software Solution should include AEPS API Integration, retailer onboarding, distributor management, wallet management, commission management, settlement management, transaction history, real-time reports, service activation controls, user permissions, and an Aeps admin panel. These features help businesses manage their complete AEPS network from one place.
A White Label AEPS B2B Software can also allow businesses to operate the Aeps platform under their own brand, including their business name, logo, domain, and customized user interface. This can be useful for companies that want to build their own branded AEPS service without developing every component of the platform from the beginning.
Security and scalability are equally important when selecting an Noble web studio is a AEPS B2B Software Provider. Businesses should consider secure authentication, biometric-device compatibility, best Aeps API reliability, transaction monitoring, role-based access, reporting, reconciliation, technical support, and infrastructure capable of handling increasing transaction volumes.
Noble Web Studio provides AEPS B2B software solutions for businesses that want to build and manage a structured digital banking network. Its AEPS solutions can support requirements such as Aeps Admin Panel, Master Distributor, Distributor and Retailer management, AEPS API integrate, wallet and commission management, transaction reporting, biometric-device integration, white label Aeps functionality, and other fintech services.
The right AEPS B2B Software can help businesses create a more organized retailer network, simplify transaction management, automate commission workflows, and provide a scalable foundation for digital banking services. Whether you are launching a new AEPS business, expanding an existing fintech network, or adding AEPS to a multi service Aeps B2B platform, choosing software that combines technology, Aeps API integrated, network management, security, reporting, and scalability is essential for long-term operations.
In this complete guide, you will learn about AEPS B2B Software, features and benefits, modules, API integration, retailer and distributor management, white label Aeps software options, commission management, wallet management, security, development, implementation, and cost so you can understand what a complete AEPS B2B platform should offer for your business.
What Is AEPS B2B Software
AEPS B2B software is a business-to-business digital platform that allows companies, fintech firms, and aggregators to empower a network of local agents and retailers to offer basic banking services through the Aadhaar Enabled Payment System.
AEPS B2B Software Work
AEPS B2B software works by linking local retail agents to the National Payments Corporation of India (NPCI) network, turning local shops into mini-banks that process cardless transactions via biometric fingerprint or iris authentication.
How the Workflow Operates
- Customer Request: A customer visits a local retail agent or Business Correspondent (BC) to perform a banking transaction.
- Data Input: The customer provides their Aadhaar number, bank name, and the transaction type (such as cash withdrawal or balance check).
- Biometric Verification: The customer scans their finger or eye on a certified biometric device (like Mantra or Morpho) connected to the agent’s system.
- NPCI Routing: The AEPS B2B Software securely routes the encrypted biometric and banking data through API integration to the NPCI and the respective customer’s bank.
- Instant Settlement: The bank approves or declines the transaction in real time, and funds are credited or debited instantly while commissions update in the agent’s digital wallet.
AEPS Services Supported by B2B Software
Aadhaar Enabled Payment System (AePS) B2B software empowers local retail shops and businesses to function as mini-banks using biometric authentication via the National Payments Corporation of India (NPCI) network.
Core AePS Services Supported
- Cash Withdrawal: Allows customers to withdraw money from their bank accounts using their Aadhaar number and fingerprint scan.
- Cash Deposit: Enables users to deposit cash directly into Aadhaar-linked bank accounts through the agent network.
- Balance Inquiry: Provides customers with instant, live updates of their bank account balance.
- Mini Statement: Displays or prints a brief history of recent transactions on the customer’s account.
- Aadhaar Pay: Lets merchant and retail shop owners accept direct digital payments from customers through biometric confirmation.
- Aadhaar-to-Aadhaar Fund Transfer: Supports seamless domestic remittances and money transfers between accounts.
Documents Required for AEPS B2B Software
Setting up an Aadhaar Enabled Payment System (AePS) B2B software platform or best Aeps admin panel requires submitting personal and corporate KYC documents, along with specific hardware and technical verifications.
Personal & Identity KYC Documents
- Aadhaar Card: Mandatory for individual or director identity verification; must be actively linked to a working mobile number for OTP authentication.
- PAN Card: Required for tax compliance, identity verification, and financial tracking.
- Passport-Sized Photographs: Recent photos of the applicant, partners, or company directors.
- Contact Details: An active email address and mobile number registered with the applicant’s Aadhaar.
Business & Banking Proofs
- Bank Account Proof: A cancelled cheque, active bank passbook copy, or recent bank statement for daily commission payouts and transaction settlements.
- Business Registration Proof: Official establishment documents such as a GST Registration Certificate, Udyam Registration, or Shop & Establishment License.
- Business Address Proof: Recent utility bills (electricity or water) matching the operational business location.
Hardware & Technical Requirements
- Certified Biometric Scanner: A UIDAI and STQC-certified Level 1 (L1) fingerprint or Aeps iris scanner (such as Mantra).
- Registered Device (RD) Service: Active device driver registration and serial number integration via the official RD service portal.
- Computing Device: A Windows PC/laptop or an Android smartphone/tablet equipped with USB OTG support.
- Internet Connectivity: A stable, high-speed broadband or mobile data connection for real-time National Payments Corporation of India (NPCI) authentication.
- Secure Hosting Server: For white label Aeps b2b or fast Aeps API deployments, a secure Linux or Windows cloud server supporting encrypted SSL/TLS protocols.
Who Can Use AEPS B2B Software
AEPS B2B software is primarily used by fintech entrepreneurs, distributors, local retailers, and Noble web studio to offer cardless, biometric banking services.
Key Users of AEPS B2B Software
- Fintech Startups and Entrepreneurs: Companies that purchase white label AEPS b2b software or reliable Aeps API to brand and launch their own customized digital banking and payment applications without needing an independent banking license.
- Distributors and Super Distributors: Network managers who use multi-layered Aeps B2B portal access to onboard, oversee, and track commissions for a downline network of local merchants and retail agents.
- Retailers and Local Shop Owners: Kirana, medical, and general store owners who turn their storefronts into mini-ATMs to process cash withdrawals, balance inquiries, and deposits for customers while earning transaction commissions.
- CSC and E-Mitra Operators: Common Service Centre operators who deliver essential banking and digital financial services to unbanked, rural, or underserved populations.
- Business Correspondents (BCs) and Certified Agents: Authorized individuals or corporate entities designated to provide doorstep or localized banking services via biometric scanners.
Why Use AEPS B2B Software
AEPS B2B software lets businesses and fintech networks offer biometric-based banking services (like cash withdrawals, balance inquiries, and mini-statements) using Aadhaar verification.
Why Use AEPS B2B Software?
- Financial Inclusion: AEPS B2B software extends basic banking services to rural and unbanked populations who lack physical bank branches.
- New Revenue Streams: AEPS B2B software allows businesses and network administrators to earn a commission on every successful transaction processed by their agents.
- Increased Customer Footfall: AEPS B2B software turns local retail shops into micro-ATM touchpoints, bringing more customers through the door to boost main business sales.
- Secure and Fraud-Resistant: AEPS B2B software uses government-backed Aadhaar fingerprint or iris biometric authentication, reducing transaction errors and fraud.
- Low Operational Costs: AEPS B2B software bypasses the need to build expensive physical bank branches by decentralizing services through existing merchant networks.
- Centralized Management: AEPS B2B software gives Aeps admins a single Aeps dashboard to Aeps onboard agents, automate settlements, track earnings, and monitor daily activity.
Key Aspects of AEPS B2B Software
AEPS B2B software is a white-label or portal-based Aeps fintech platform that allows businesses, local merchants, and agents to offer cardless, biometric-authenticated banking and payment services using the Aadhaar Enabled Payment System.
Software & Technical Features
- Biometric Integration: Connects seamlessly with UIDAI-certified fingerprint scanners and iris devices.
- Multi-Bank Support: Enables interoperable transactions across multiple banking partners through a single platform.
- Real-Time Processing: Connects directly with the National Payments Corporation of India (NPCI) network for instant clearance.
- Hierarchy & Commission Management: Features multi-level downline networks (Admin, Distributors, Retailers) with automated commission crediting.
Key Benefits
- Enhanced Security: Eliminates physical cards and PINs, relying strictly on Aadhaar biometric authentication to reduce fraud.
- Financial Inclusion: Expands essential banking access to unbanked and rural populations via local retail touchpoints.
- Cost-Effective: Removes the need for heavy traditional ATM or physical banking infrastructure.
AEPS B2B Software for Distributors, Retailers & Fintech Businesses
AEPS B2B software is a centralized digital banking platform that empowers fintech companies, distributors, and local retailers to offer cardless, biometric-authenticated financial services using the Aadhaar Enabled Payment System.
Key Features for the B2B Hierarchy
- Multi-Tier Management: Supports hierarchical role structures including best Aeps Admin, Master Distributors, Super Distributors, Distributors, and Retailers/CSPs.
- Automated Commission Engine: Configures and disburses real-time or periodic commission slabs across the entire distribution network.
- Wallet & Ledger Systems: Provides real-time fund settlements (T+0), automated payout tracking, and balanced digital ledgers.
- White-Label & API Support: Allows businesses to launch fully branded portals, admin panels, and mobile apps using robust AEPS API.
- Security & Compliance: Built on NPCI- and RBI-compliant architecture featuring 256-bit encryption and UIDAI-certified biometric device compatibility.
AEPS B2B Software for Different Business Models
AEPS B2B software empowers businesses to offer Aadhaar-based banking and biometric financial services through multi-tiered operational structures.
Business Models for AEPS B2B Software
- Single Merchant / Retailer Model: Local shop owners and Kirana stores use merchant-level panels or mobile apps connected to a biometric scanner to act as a micro-ATM for cash withdrawals, balance inquiries, and mini-statements.
- Multi-Level Reseller / Distributor Network: Hierarchical setups consisting of Super Distributors, Master Distributors, and Retail/Agent networks. Administrators manage agent onboarding, automated commission splits, and transaction monitoring across the chain.
- White-Label SaaS Model: Fintech startups and neo-banks brand the entire Aeps service platform with their own logo, domain, and custom UI, utilizing the Noble web studio backend NPCI-approved infrastructure and Aeps bank API without independent certification.
- Enterprise / API Integration Model: Large-scale businesses integrate AEPS API directly into their existing proprietary ERP or multi-service consumer apps to bundle banking with utility payments (BBPS), DMT, and recharges.
AEPS B2B Software for Retailers and Distributors
AEPS (Aadhaar Enabled Payment System) B2B software is a centralized digital Aeps admin platform that enables retailers, distributors, and fintech enterprises to offer cardless, biometric-based banking and best micro ATM services.
Core Features for Retailers and Distributors
- Basic Banking Services: Facilitates biometric cash withdrawals, balance inquiries, mini-statements, and Aadhaar Pay directly from local retail shops.
- Hierarchical Management: Allows administrators and master distributors to manage multi-tier networks (Super Distributors, Distributors, and Retailers/CSPs) and assign member IDs.
- Commission & Wallet System: Automates real-time commission calculations, slab distributions, and instant wallet settlements (T+0).
- Security & Compliance: Uses 256-bit data encryption, STQC-certified L1 biometric device integration, and NPCI/RBI-compliant infrastructure.
- Multi-Service Add-ons: Bundles additional digital solutions like BBPS utility bill payments, mobile/DTH recharges, and Domestic Money Transfers (DMT).
Why Businesses are Choosing AEPS B2B Software
Businesses choose AEPS B2B Software (Aadhaar Enabled Payment System) because it turns local shops and Aeps service portals into mini-banking hubs, unlocking new revenue and expanding customer reach.
Key Reasons Businesses Choose AEPS B2B Software
- Extra Commission Revenue: Retailers and agents earn a profitable commission on every transaction, such as cash withdrawals, balance inquiries, or mini-statements.
- Increased Foot Traffic: Offering essential banking services brings more people into physical stores, which naturally boosts sales for regular retail products.
- Cardless and PIN-less Convenience: Customers do not need debit cards, credit cards, or passwords. They authenticate transactions safely using only their Aadhaar number and a fingerprint scan.
- Universal Interoperability: The platform connects to the National Payments Corporation of India (NPCI) network, allowing businesses to serve customers from almost any major bank in the country through a single dashboard.
- Low Entry Barrier: Starting operations requires minimal infrastructure typically just an internet-connected smartphone or computer and a certified biometric fingerprint scanner.
- High Security and Trust: Biometric UIDAI-authenticated verification prevents fraud and eliminates the risks tied to stolen or forgotten PINs.
- Financial Inclusion: It brings vital banking access to rural and underbanked regions that lack nearby physical bank branches or ATMs.
AEPS B2B Software Business Model
An AEPS B2B Software business model empowers enterprises and fintech startups to turn local retail shops into cardless, biometric-enabled mini-banks using the Aadhaar Enabled Payment System connected via the National Payments Corporation of India (NPCI) network.
User Hierarchy & Operational Flow
- Super Admin / Admin: The core software owner or fintech brand that manages high speed Aeps API switches, sets global commission slabs, handles banking partners, and monitors Aeps commission platform-wide compliance.
- Master Distributor: Regional or state-level partners who oversee regional zones, manage floating wallet funds, and earn override commissions on volume.
- Distributor: Area or district-level managers responsible for Aeps onboarding, KYC verification, and supporting local agents.
- Retailer / Merchant: Ground-level touchpoints (e.g., local kirana or pharmacy shops) equipped with UIDAI-certified biometric scanners to process customer transactions
- Customer: End-users who perform cardless cash withdrawals, balance inquiries, or mini-statements using their Aadhaar number and fingerprint scan.
Features AEPS B2B Software
AEPS B2B software is a centralized digital Aeps earning platform that allows businesses, fintech startups, and local merchants to offer cardless, biometric-authenticated micro-banking services like cash withdrawals and balance inquiries.
Software & Technical Features
- Biometric Integration: Connects seamlessly with UIDAI-certified fingerprint scanners and iris devices.
- Multi-Bank Routing & API Integration: Switches traffic across multiple banking partners and National Payments Corporation of India (NPCI) infrastructure to maintain high uptimes and real-time processing.
- User Hierarchy Management: Controls multi-level downline networks including Admin, Master Distributors, Distributors, and Retailers/Agents.
- Automated Commission Slabs: Calculates and credits partner or retailer commissions instantly upon transaction settlement.
- White-Label Customization: Aeps india offers fully customizable user interfaces, domains, and logos tailored for individual brand identity.
- Security & Encryption: Uses end-to-end data encryption and Aadhaar authentication to prevent fraud and ensure strict regulatory compliance.
Benefits AEPS B2B Software
AEPS B2B Software empowers fintech startups, distributors, and local retailers to offer cardless, biometric banking services directly through the National Payments Corporation of India (NPCI) network.
Key Benefits for Businesses
- Commission Earnings: Generate recurring revenue by earning attractive commission margins on every customer transaction like cash withdrawals, balance checks, or mini-statements.
- High Security: Prevent fraud and eliminate stolen PIN or password risks using UIDAI-certified biometric verification via fingerprint or iris scanners.
- Cost-Effectiveness: Avoid heavy investments in physical bank infrastructure, POS terminals, and traditional ATM setups, making it ideal for small enterprises.
- Increased Footfall: Drive more customers into local retail shops to access banking services, which subsequently boosts sales for other in-store products.
- Financial Inclusion: Bridge the rural banking gap by delivering critical cash and account services to underbanked and remote populations.
- Multi-Service Integration: Combine the top Aeps platform seamlessly with BBPS (Bharat Bill Payment System), mobile recharges, and money transfers through a unified single dashboard.
AEPS B2B software offers significant benefits for businesses, including new revenue streams from

AEPS B2B Software Development
Building a B2B Aadhaar Enabled Payment System (AEPS) software platform involves strict regulatory compliance, secure biometric integration, and a multi-tiered management architecture.
Development and Deployment Process
- Requirement Analysis & Planning: Define the scope of banking services (cash withdrawal, balance inquiry, mini statements, and fund transfers), identify target merchant/retailer hierarchies, and outline legal prerequisites.
- Design and Architecture: Structure the database, Aeps admin panels, and top Aeps API routing infrastructure. Decide between building custom banking connections or using a plug-and-play best White Label AEPS Software model.
- API Integration Layer: Connect with NPCI (National Payments Corporation of India) and bank partner switches via secure, encrypted Aeps service API endpoints to handle transaction requests and UIDAI authentication calls.
- Biometric Module Integration: Incorporate Aeps Software Development Kits (SDKs) for UIDAI-certified fingerprint and iris scanners to capture, compress, and encrypt biometric packets securely.
- Dashboard and Role Management Development: Build multi-level hierarchy panels (Admin, Master Distributors, Distributors, and Retailers/Agents) with built-in commission tracking, wallet management, and ledger reports.
- Testing and Quality Assurance: Run stress tests, security audits, and validation checks on transaction flows, data encryption, and failure/success response handling.
- Compliance and Deployment: Ensure complete adherence to RBI and NPCI guidelines, deploy servers on secure cloud infrastructure, and launch the web and Android Aeps application portals.
AEPS B2B Software Cost in India
An AEPS (Aadhaar Enabled Payment System) B2B software cost structure typically ranges from a one-time setup fee of ₹10,000 to ₹35,000 for basic Aeps API integration, ₹35,000 to ₹1,20,000 for standard Aeps B2B admin/white label Aeps portals, and ₹2,50,000 to ₹4,50,000+ for custom bank-backed enterprise solutions.
Key Cost Components
- One-Time Setup & API Integration: ₹12,000 to ₹35,000 for basic Aeps API setup connecting standard endpoints from Noble web studio.
- White-Label B2B Admin Portals: ₹35,000 to ₹1,20,000 for ready-made branded web and best Android Aeps application platforms with multi-level retailer and distributor management hierarchies.
- Custom Direct Bank API Integration: ₹2,50,000 to ₹4,50,000+ for fully custom enterprise platforms with direct bank backend connectivity.
Ongoing & Hidden Expenses
- Transaction/Commission Fees: Aeps Commission structure or per-transaction gateway fees typically range from 0.5% to 1% or a flat ₹3 to ₹5 per transaction depending on volume and service type.
- GST: An additional 18% GST applies to Aeps software setup, Aeps development, and Annual Maintenance Contract (AMC) invoices.
- Device RD Services: Biometric fingerprint scanners (like Mantra or Morpho) require annual registered device (RD) service renewals of approximately ₹375 per year per device.
- Working Capital Float: An initial security deposit or operational wallet pre-funding amount is required with the parent aggregator or bank for instant settlement processing.
AEPS B2B Software Commission Structure
An AEPS B2B Software commission structure is a tiered payout model where transaction rewards scale based on cash withdrawal slabs, typically offering retailers ₹2 to ₹15 per transaction while allowing admin and white-label owners to configure margins across agent hierarchies.
Typical Retailer Commission Slabs
- ₹100 to ₹999: Earns a base commission of ₹2 per transaction.
- ₹1,000 to ₹1,499: Earns a commission of ₹3 per transaction.
- ₹1,500 to ₹1,999: Earns a commission of ₹4.50 per transaction.
- ₹2,000 to ₹2,499: Earns a commission of ₹5.50 per transaction.
- ₹3,000 and Above (Higher Slabs): Scales up incrementally, reaching max payouts of ₹13 to ₹15 for higher value withdrawal brackets.
Hierarchy & Distribution Commission Flow
- Retailers / Agents: Process the biometric Aadhaar transaction at the storefront and collect the direct per-slab transaction commission.
- Distributors / Block Partners: Manage localized retailer networks and receive an override commission or margin (a small percentage or flat cut) on every transaction processed by their mapped agents.
- Master Distributors (MDs): Supervise district-level or large networks, often earning flat margins (such as up to ₹15 or structured overrides) per withdrawal across their downline.
AEPS B2B Software Security Features
Aadhaar Enabled Payment System (AEPS B2B Software) relies on multi-layered security frameworks to ensure secure, cardless micro-banking transactions.
Key Security Features
- Biometric Authentication: Verifies customer identity via unique fingerprint or iris scans processed through UIDAI servers, removing the need for a physical debit card or ATM PIN.
- Registered Device (RD) Integration: Communicates strictly through certified RD services that encrypt biometric templates directly at the hardware device level prior to internet transmission.
- End-to-End Encryption (E2EE): Secures all data in transit using rigorous protocols (such as SSL/TLS) across the NPCI gateway to prevent packet sniffing or data interception.
- Role-Based Access Control (RBAC): Restricts access to sensitive Aeps administrative panel, wallet load options, and ledger configurations according to specific user permissions (retailer, distributor, or admin).
- Real-Time Fraud Monitoring: Employs AI-driven surveillance and automated logs to flag abnormal login patterns, multiple rapid failed authentications, or suspicious velocity in transactions.
- Regulatory Compliance: Adheres strictly to guidelines set by the Reserve Bank of India and NPCI, including mandatory KYC/AML protocols and multi-factor authentication for administrative overrides.
AEPS B2B Software Compliance & Regulatory Considerations
AEPS B2B software must comply with multi-layered regulations from the Reserve Bank of India (RBI), National Payments Corporation of India (NPCI), and UIDAI to ensure legal and secure operations.
- Key Regulatory Bodies & MandatesRBI (Reserve Bank of India): Governs overall banking relationships, enforces strict agent and merchant KYC, and mandates continuous transaction monitoring.
- NPCI (National Payments Corporation of India): Oversees the underlying payment rail, technical protocols, and enforces the operational “One-Agent-One-Bank” linking rule to curb misuse.
- UIDAI (Unique Identification Authority of India): Controls Aadhaar authentication standards, strictly prohibiting the local storage of raw biometric data.
- DPDP Act: Governs overall data privacy, requiring secure databases and minimal retention periods for sensitive customer transaction logs.
Essential Software Compliance Features
- L1 Biometric Devices: Platforms must integrate only with STQC-certified L1 registered fingerprint or iris scanners.
- Encrypted Data Flow: Biometric packets must be encrypted at the device level and passed directly via licensed APIs without local caching.
- AI Fraud Monitoring: Real-time tracking and automated anomaly detection must be active within the admin panel to isolate suspicious agent behavior.
- Transparent Audit Trails: Comprehensive logs of user consent and transaction states must be maintained for regulatory reviews.
AEPS B2B Software Reporting & Reconciliation
Effective AEPS B2B Software reporting and reconciliation ensures financial accuracy and real-time tracking between retail agents, switch Noble web studio server, and the NPCI network.
Core Reporting Features
- Real-Time Logs: Track live status for cash withdrawals and balance checks.
- Ledger Summaries: View automated retailer and distributor commission splits.
- Dispute Trackers: Monitor flagged or failed biometric authentication attempts.
Reconciliation Workflows
- Switch File Matching: Compare trusted Aeps API responses with bank settlement files daily.
- NTSL Integration: Import National Transaction Settlement Luxemburg/System reports.
- Exception Handling: Auto-identify mismatched RRN (Retrieval Reference Numbers).
Automation & Settlement
- T+0 Payouts: Instant ledger adjustments for successful transactions.
- TTUM Generation: Create Two-Way Transaction Union Management files for banks.
- Audit Trails: Maintain compliance logs for RBI and NPCI guidelines.
White Label AEPS B2B Software
A White Label AEPS B2B Software is a pre-built, customizable digital Aeps banking platform that lets you launch your own branded Aadhaar Enabled Payment System (AEPS) and micro-banking business without writing code from scratch.
Core Features & Services
- Banking Transactions: Enable biometric cash withdrawals, balance inquiries, mini-statements, and Aadhaar Pay using customer fingerprint authentication.
- Value-Added Services: Bundle utility bill payments via best BBPS, mobile/DTH recharges, Domestic Money Transfer (DMT), and travel bookings.
- Hierarchy Management: Control multi-tier user networks including super distributors, distributors, and retail agents from a central admin panel.
- Custom Branding: Apply your own company logo, custom domain name, and color scheme to web and mobile portals.
Ready-Made vs Custom AEPS B2B Software
Ready-made (white-label) AEPS B2B Software is ideal for fast, low-cost market entry, while custom development fits enterprises requiring unique workflows, robust scalability, and direct Aeps banking API ownership.
Comparison Table: Ready-Made vs Custom AEPS B2B Software
| Feature / Parameter | Ready-Made / White-Label AEPS Software | Custom AEPS Software Development |
|---|---|---|
| Initial Cost | Lower (₹15,000 – ₹60,000) | Higher (₹1,00,000 – ₹4,500,000+) |
| Deployment Time | Fast (1 to 7 days) | Slow (4 to 12 weeks) |
| Branding & UI | Limited to logo, domain, and color changes | Fully tailored user experience and distinct interface design |
| Customization | Restricted to Noble web studio-provided modules and features | Unlimited features, custom hierarchies, and tailored logic |
| API Control | Shared or Noble web studio-managed switch/API | Direct integration with banking partners (e.g., ICICI, Yes Bank) |
| Maintenance & Updates | Handled completely by the Noble web studio | Managed in-house or via a dedicated retainer contract |
| Scalability | Bound by the architecture limits of the turnkey platform | Highly scalable to match expanding transaction volumes |
Key Takeaways
- Ready-Made is best for startups or local distributors wanting to launch an agent network quickly with minimal upfront capital.
- Custom Software fits mature fintech enterprises needing proprietary security rules, specific multi-level commission structures, and independence from a Noble web studio
Noble Web Studio One of The Right AEPS B2B Software Provider
Noble Web Studio one of the right AEPS B2B Software Provider requires evaluating critical factors like security compliance, transaction success rates, and robust admin controls to ensure smooth digital banking operations.
Key Factors to Choose the Noble Web Studio
Security & Regulatory Compliance
- Must adhere to NPCI and UIDAI guidelines.
- Look for strong data encryption, two-factor authentication (2FA), and secure biometric data handling.
Transaction Success & Uptime
- High-level Aeps admin software should feature multi-bank routing to guarantee high uptime (98% or above) and fast transaction processing speeds.
- Real-time transaction tracking and instant failure resolution mechanisms.
Admin & User Management Panel
- Comprehensive Aeps B2B admin dashboard for managing retailer and distributor hierarchies, monitoring wallet balances, and setting commission structures.
- Automated reporting and reconciliation tools for daily transaction auditing.
API Integration & Scalability
- Seamless AEPS API Integration to merge services with Micro-ATMs, DMT (Domestic Money Transfer), BBPS, and utility bill payments.
- Scalable infrastructure capable of accommodating growing transaction volumes and expanding agent networks.
Pricing & Commission Transparency
- Clear Aeps setup cost, white label Aeps fees, and recurring annual maintenance charges without hidden expenses.
- Competitive commission margins for retailers and distributors.
Technical Support
- Responsive, reliable 24/7 technical and operational assistance to troubleshoot downtime or transaction stuck issues immediately.
Read Also : Top 10 AEPS Service Provider Companies in India 2025
Why Noble Web Studio Is a Trusted AEPS B2B Software Solution
Noble Web Studio is a trusted AEPS B2B Software solution is a secure, NPCI-certified digital banking platform that empowers local retailers, distributors, and fintech startups to turn everyday storefronts into functional mini-ATMs and micro-banking service points.
Key Reasons Why AEPS B2B Software is Trusted
- Biometric & Regulatory Security: Utilizing Aadhaar-based fingerprint or iris authentication backed by strong encryption ensures that cardless transactions are highly secure and fully compliant with RBI and National Payments Corporation of India guidelines.
- High Uptime & Success Rates: Noble web studio offer multi-bank routing systems that deliver rapid processing speeds and reliable transaction success rates exceeding 98% to 99.9%.
- Instant Settlements & Commission Tracking: Automated reporting, real-time transaction tracking, and immediate merchant settlements ensure transparent commission earnings (often up to ₹15–₹17 per transaction) for agents and distributors.
- Seamless Ecosystem Integration:Noble web studio easily integrate with other financial modules like BBPS bill payments, mobile recharges, and money transfers to build a comprehensive, one-stop financial service portal.
- Financial Inclusion & Scalability: It extends basic banking infrastructure (cash withdrawals, balance inquiries, mini-statements) to unbanked and rural populations while letting startups scale their own white-label branded applications.
Read Also :
Future Trends in AEPS B2B Software
Future trends in AEPS B2B Software center on advanced biometric security, artificial intelligence, and wider interoperability to scale rural and assisted digital banking across India.
Key Future Trends in AEPS B2B Software
- Mandatory Liveness Detection: Modern AEPS Software integrates deepfake-resistant anti-spoofing protocols to block fake or cloned fingerprint attempts during customer authentication.
- AI Fingerprint Matching: Advanced machine learning and AI algorithms reduce false authentication rejections and improve scanning success rates for rural users.
- AEPS 2.0 Interoperability: Enhanced routing frameworks expand seamless connectivity across commercial banks, NBFCs, and millions of Jan-Dhan accounts.
- AI Fraud Analytics: Real-time monitoring tools track agent hierarchies and flag suspicious transactions instantly to prevent financial fraud.
- Automated Commission and Settlement: Top Aeps Admin panel feature automated split-commission structures and instant real-time wallet settlements for master distributors and sub-agents.
Core Capabilities Driving Demand
- Cardless Transactions: Customers complete cash withdrawals, balance checks, and mini-statements using only an Aadhaar number and fingerprint scan.
- White-Label Customization: Fintech companies can launch branded mini-banking mobile applications and admin dashboards.
- Multi-Bank Routing: High-uptime Aeps API architecture switches dynamically between banking partners to maintain high transaction success rates.
AEPS B2B Software
Looking for reliable AEPS B2B Software for your fintech business? Get a professional AEPS solution designed for retailers, distributors and growing digital service businesses. Connect with our team to discuss your requirements, pricing and software setup.
Final Thoughts
Choosing the right AEPS B2B Software is an important decision for fintech companies, startups, distributors, retailers, CSP networks, and businesses that want to provide Aadhaar-enabled banking services through their own digital platform. A professional B2B AEPS solution should combine transaction management, retailer and distributor operations, commissions, reporting, security, and smooth Aeps API connectivity in one centralized system.
A complete AEPS B2B Software Solution should support essential services such as cash withdrawal, balance enquiry, mini statement, fund transfer, and other supported best AEPS services, while providing the business with the technology required to manage its complete distribution network. Key modules can include an AEPS Admin Panel, Retailer Panel, Distributor Panel, AEPS API Integrating, biometric device support, wallet management, commission management, settlement management, transaction reports, user management, and real-time monitoring.
AEPS B2B software is a modern Aeps platform that lets businesses and local retailers offer basic banking services like cash withdrawals, balance checks, and mini-statements using customer Aadhaar numbers and fingerprint verification.
For a growing fintech business, scalability is just as important as basic features. The software should make it easier to Aeps onboarded and manage retailers and distributors, configure commission structures, monitor transactions, handle settlements, generate reports, and maintain centralized administrative control. Noble Web Studio’s existing fast AEPS B2B platform material specifically highlights agent management, commission setup, reporting, faster Aeps API integration, and centralized administration.
Noble Web Studio provides AEPS B2B Software and related fintech solutions for businesses that want to launch, customize, or expand their digital banking operations. Its AEPS solutions can be configured around requirements such as Aeps B2B admin management, retailer and distributor management, low cost AEPS API integration, transaction processing, commission management, wallet operations, reporting, biometric authentication, and white-label functionality.
Before selecting Noble web studio is an AEPS B2B Software Provider, businesses should compare the complete technology solution rather than focusing only on software price. Important considerations include AEPS API connectivity, transaction reliability, security, biometric compatibility, user hierarchy, retailer management, distributor management, commission configuration, settlement options, reporting, customization, scalability, technical support, and applicable banking or network requirements.
Whether you are starting AEPS business, adding AEPS to an existing best Aeps fintech platform, or expanding a large retailer and distributor network, the right AEPS B2B Software can provide a centralized technology foundation for managing your operations. A properly designed Aeps platform can bring banking transactions, users, commissions, wallets, reports, and administrative controls together in one structured ecosystem.
With Noble Web Studio, businesses can build or customize an AEPS B2B Software Solution according to their branding, business model, user hierarchy, integration requirements, and future expansion plans. The right combination of fast AEPS software, API integration, admin controls, retailer management, transaction monitoring, and scalable infrastructure can create a strong foundation for a digital banking business.
Frequently Asked Questions About AEPS B2B Software
AEPS B2B Software is a platform that helps fintech businesses manage AEPS services, retailers, distributors, wallets, commissions, transactions, settlements, and reports from one centralized system.
Key features include retailer and distributor management, wallet management, commission management, AEPS transactions, onboarding, settlement, reporting, dashboards, API integration, reconciliation, and role-based access.
Yes. It can provide a multi-level hierarchy for managing master distributors, distributors, retailers, their services, wallets, commissions, transactions, and reports from a centralized admin panel.
Yes, when white-label functionality is provided. Businesses can use their own brand name, logo, domain, and supported branding elements while using the underlying AEPS software infrastructure.
It can simplify registration, KYC collection, document submission, verification, approval, service activation, and user management through a centralized onboarding workflow.
Yes. Wallet management can track partner balances, credits, debits, transaction deductions, and other supported wallet activities for retailers and distributors.
The software can allow administrators to configure commission rules for different users or transaction types and automatically record applicable commissions for eligible transactions.
Yes, AEPS platforms can support services such as cash withdrawal, balance enquiry, and mini statement through connected AEPS infrastructure, subject to the services enabled by the Noble web studio.
The software records transaction details and provides status information such as successful, failed, pending, or other supported states, helping administrators and retailers track transactions.
It can support Aadhaar Pay and other available AEPS services when they are enabled through the connected API or banking infrastructure. Supported services vary by Noble web studio
.
Some platforms provide automated settlement and reconciliation features that help match transaction records with settlement data. Actual settlement timing depends on the connected Noble web studio.
Yes. It can provide reports for transactions, commissions, wallets, settlements, retailers, distributors, and other supported business activities.
Yes. AEPS B2B software can integrate with supported AEPS APIs and banking infrastructure to process transactions, receive responses, check status, and manage connected services.
Yes. Separate dashboards can provide administrators, distributors, and retailers with access to the features and information permitted for their respective roles.
Security can include HTTPS, authentication, role-based access, secure API credentials, access controls, transaction monitoring, and protected data handling. Security features depend on the software implementation.
Yes. Depending on the Noble web studio, an AEPS B2B platform can combine AEPS with services such as micro ATM, BBPS, recharge, DMT, Aadhaar Pay, and other fintech services.
The cost depends on features, customization, white-label requirements, API integrations, users, hosting, support, and additional services. Noble web studio may offer different pricing models based on business requirements.
Yes. It can support fintech startups, distributors, service providers, and businesses managing retailer networks, provided the platform offers suitable scalability, infrastructure, services, and support.
Compare AEPS services, retailer and distributor management, wallets, commissions, API integration, settlements, security, reports, scalability, white-label options, pricing, documentation, and technical support before choosing a Noble web studio.
Noble web studio can be evaluated for its available AEPS B2B features, retailer and distributor management, wallet and commission management, API integration, transaction reporting, security, white-label capabilities, pricing, and support.